Title
Zelle® Responds to New York Attorney General's Copycat Politically-Motivated Lawsuit
Press Body

NEW YORK – Zelle® released the following statement regarding the politically-motivated lawsuit filed by the New York Attorney General that fails to acknowledge that scams don’t start on Zelle, they start with criminals manipulating people long before dollars move.

Statement attributable to Zelle spokesperson

“Zelle® leads the fight to stop fraud and scams in America. This lawsuit is a political stunt to generate press, not progress. The Attorney General wants to hand criminals a blueprint for guaranteed payouts with no consequences, opening the floodgates to more scams, not less. That’s bad policy and puts consumers at greater risk. This is nothing more than a copycat of the Consumer Financial Protection Bureau lawsuit that was dismissed in March. Despite the Attorney General’s assertions, they did not conduct an investigation of Zelle. Had they conducted an investigation, they would have learned that more than 99.95 percent of all Zelle transactions are completed without any report of scam or fraud – which leads the industry. The Attorney General should focus on the hard facts, stopping criminal activity and adherence to the law, not overreach and meritless claims.”

About Zelle®

Zelle® powers fast, reliable person-to-person digital payments, moving more than $1 trillion between millions of consumer and small business accounts at United States banks and credit unions. Available through a network of more than 2,300 financial institutions, Zelle® enables people to send and receive money directly – without cash, checks or third-party apps. Zelle® is owned and operated by Early Warning Services, LLC, which works with America’s banks, credit unions and government agencies to drive prosperity, deliver bold innovation and improve how payments are made. Learn more at www.zelle.com.

By Undermining Zelle, the CFPB’s Lawsuit will Empower Criminals, Harm Consumers and Small Businesses, and Hurt Community Banks


NEW YORK – Zelle® released the following statement regarding the lawsuit filed by the Consumer Financial Protection Bureau (CFPB) that will harm the very consumers the Bureau is required to protect, hurt America’s small businesses and make it harder for community and minority-owned banks and credit unions to compete:

Statement attributable to Jane Khodos, Zelle spokesperson

For more information visit: www.zellepay.com/americans-rely-on-zelle

“The CFPB’s attacks on Zelle are legally and factually flawed, and the timing of this lawsuit appears to be driven by political factors unrelated to Zelle. Zelle leads the fight against scams and fraud and has industry-leading reimbursement policies that go above and beyond the law. The CFPB’s misguided attacks will embolden criminals, cost consumers more in fees, stifle small businesses and make it harder for thousands of community banks and credit unions to compete. Zelle is relied upon by 143 million enrolled American consumers and small businesses, and we are fully prepared to defend this meritless lawsuit to ensure their service does not suffer.”

Key Points:

  • We have made every effort to engage and cooperate with the CFPB on this matter, however they fail to acknowledge Zelle is an essential part of protecting Americans from fraud and scams due to our highly effective multilayered fraud and scam prevention countermeasures. The Bureau also fails to acknowledge our consumer reimbursement policies that already go beyond legal and regulatory requirements.
     
  • American consumers value Zelle as a reliable, convenient, trusted, and free peer-to-peer money transfer service.1 In fact, in 2023, despite a 27% increase in transaction volume, reports of scams and fraud decreased by nearly 50%, resulting in 99.95% of payments being sent without a report of scams and fraud.
     
  • The CFPB will also encourage rather than prevent criminal activity by incentivizing criminals to make false claims against banks and credit unions, while also removing incentives for consumers to exercise caution when sending money. And by requiring financial institutions to pay for the actions of criminals, thousands of financial institutions that provide Zelle – including many community and minority-owned banks and credit unions – will be forced to choose between offering Zelle or increasing fees for consumers to move money and pay everyday expenses. The CFPB’s attacks will unfairly shift the financial burden of criminal activity to community and minority-owned banks and credit unions – something smaller financial institutions cannot afford.
     
  • Small businesses already face enough challenges, but the CFPB would have them face even more. In the first half of 2024 alone, small businesses conducted nearly 244 million transactions using Zelle, moving $129.5 billion dollars. Small business owners in communities across the U.S. rely on Zelle’s unique features to provide their customers with flexible ways to pay, to give their dedicated employees an on-the-spot bonus, and to quickly send money for a last-minute delivery.  If banks are forced to stop offering Zelle, it would take away a valuable, reliable and needed tool for America’s Main Street – the backbone of the U.S. economy.
     
  • Zelle reimburses customers for all instances of fraud as required by the law under the Electronic Funds Transfer Act and Reg E, and today’s litigation from the CFPB does not dispute that fact. Zelle also goes above and beyond what is required by law and reimburses customers for certain types of scams where the customer authorized the transaction. Through this lawsuit, the CFPB would be simultaneously creating and enforcing entirely new legal requirements that go well beyond what Congress authorized the CFPB to do. This lawsuit would be part of the CFPB’s pattern and practice of regulatory overreach where the CFPB is attempting to impermissibly expand the law to require banks to reimburse consumers for transactions they authorized, which goes well beyond the clearly defined requirements established by Congress in the Electronic Funds Transfer Act.


  1. Based on a Q4 2023 survey of financial institutions offering Zelle® to their customers, 99.44% of consumer saving and checking accounts linked to Zelle® are not charged a fee to send, receive, or request money.
Title
Zelle® Responds to the CFPB’s Meritless Lawsuit
Press Body

NEW YORK – Zelle® released the following statement regarding the lawsuit filed by the Consumer Financial Protection Bureau (CFPB) that will harm the very consumers the Bureau is required to protect, hurt America’s small businesses and make it harder for community and minority-owned banks and credit unions to compete:

Statement attributable to Jane Khodos, Zelle spokesperson

For more information visit: www.zellepay.com/americans-rely-on-zelle

“The CFPB’s attacks on Zelle are legally and factually flawed, and the timing of this lawsuit appears to be driven by political factors unrelated to Zelle. Zelle leads the fight against scams and fraud and has industry-leading reimbursement policies that go above and beyond the law. The CFPB’s misguided attacks will embolden criminals, cost consumers more in fees, stifle small businesses and make it harder for thousands of community banks and credit unions to compete. Zelle is relied upon by 143 million enrolled American consumers and small businesses, and we are fully prepared to defend this meritless lawsuit to ensure their service does not suffer.”

Key Points:

  • We have made every effort to engage and cooperate with the CFPB on this matter, however they fail to acknowledge Zelle is an essential part of protecting Americans from fraud and scams due to our highly effective multilayered fraud and scam prevention countermeasures. The Bureau also fails to acknowledge our consumer reimbursement policies that already go beyond legal and regulatory requirements.
     
  • American consumers value Zelle as a reliable, convenient, trusted, and free peer-to-peer money transfer service.1 In fact, in 2023, despite a 27% increase in transaction volume, reports of scams and fraud decreased by nearly 50%, resulting in 99.95% of payments being sent without a report of scams and fraud.
     
  • The CFPB will also encourage rather than prevent criminal activity by incentivizing criminals to make false claims against banks and credit unions, while also removing incentives for consumers to exercise caution when sending money. And by requiring financial institutions to pay for the actions of criminals, thousands of financial institutions that provide Zelle – including many community and minority-owned banks and credit unions – will be forced to choose between offering Zelle or increasing fees for consumers to move money and pay everyday expenses. The CFPB’s attacks will unfairly shift the financial burden of criminal activity to community and minority-owned banks and credit unions – something smaller financial institutions cannot afford.
     
  • Small businesses already face enough challenges, but the CFPB would have them face even more. In the first half of 2024 alone, small businesses conducted nearly 244 million transactions using Zelle, moving $129.5 billion dollars. Small business owners in communities across the U.S. rely on Zelle’s unique features to provide their customers with flexible ways to pay, to give their dedicated employees an on-the-spot bonus, and to quickly send money for a last-minute delivery.  If banks are forced to stop offering Zelle, it would take away a valuable, reliable and needed tool for America’s Main Street – the backbone of the U.S. economy.
     
  • Zelle reimburses customers for all instances of fraud as required by the law under the Electronic Funds Transfer Act and Reg E, and today’s litigation from the CFPB does not dispute that fact. Zelle also goes above and beyond what is required by law and reimburses customers for certain types of scams where the customer authorized the transaction. Through this lawsuit, the CFPB would be simultaneously creating and enforcing entirely new legal requirements that go well beyond what Congress authorized the CFPB to do. This lawsuit would be part of the CFPB’s pattern and practice of regulatory overreach where the CFPB is attempting to impermissibly expand the law to require banks to reimburse consumers for transactions they authorized, which goes well beyond the clearly defined requirements established by Congress in the Electronic Funds Transfer Act.
     

1 Based on a Q4 2023 survey of financial institutions offering Zelle® to their customers, 99.44% of consumer saving and checking accounts linked to Zelle® are not charged a fee to send, receive, or request money.

Error Landing Page

Sorry we couldn't find that page.

Visit zelle.com

Zelle® Network Processor Partner | Fiserv

Zelle Network® Processor Partner

FISERV

By selecting 'Submit', you agree that the information you have provided is subject to our Privacy Notice. You also agree to receive the communications you have requested (including marketing communications).

Zelle Network Hard Copy Forms/Offline Privacy Notice for B2B California Residents

Zelle Network Hard Copy Forms/Offline Privacy Notice for B2B California Residents

Updated: August 17, 2026

This Privacy Notice applies to the Personal Information of B2B California residents who complete hard copy forms for the Zelle Network® (e.g., participating financial institutions) (referred to as “Form(s)” from here on out).

Pursuant to the California Consumer Privacy Act (CCPA), its implementing regulations, and as modified by the California Privacy Rights Act (CPRA), this Privacy Notice is intended to inform California residents of the Personal Information we collect, how it’s used and disclosed, and the rights you have in regard to such information.

We strive for transparency but if anything remains unclear, do not hesitate to contact us at the email address below with any questions or feedback you may have.

As a visitor to our website, our Zellepay.com Website Privacy Notice also applies. Click here to learn more.

By submitting a Form(s), you agree that the information you have provided is subject to this Privacy Notice. In other words, please do not submit the Form if you do not agree with this Privacy Notice.

What do you want to learn more about?

Table of Contents

  1. When this Privacy Notice applies
  2. What Personal Information is
  3. Personal Information we’ve collected, used, and/or disclosed
  4. B2B California residents’ privacy rights
  5. Your choices
  6. How we protect Personal Information
  7. Where Personal Information is stored
  8. Changes to this Privacy Notice
  9. How to contact us

1. When this Privacy Notice applies

This Privacy Notice applies to the Personal Information of business-to-business (“B2B”) California residents who complete hard copy forms for the Zelle Network® (e.g., participating financial institutions) (referred to as “Form(s)” from here on out).

As a visitor to our website, our Zelle.com Website Privacy Notice also applies. Click here to learn more.

2. What Personal Information is

For the purpose of this Privacy Notice, “Personal Information” means information that identifies or can be used to identify you directly or indirectly. Examples of Personal Information include, but are not limited to, first and last name, your title, business email address, business telephone number, business address. 

Personal Information does not include information obtained from public sources or information that is made available by federal, state, or local governments. Personal Information also does not include deidentified, anonymized, or aggregate information.

3. Personal Information we’ve collected, used, and/or disclosed

If you’ve submitted a Form(s) in the past 12 months for the Zelle Network®, we may have collected, used, and/or disclosed the following categories of Personal Information about you for a business purpose(s):

  • Personal and online identifiers
    • Examples:
      • Name, title, company email address
    • Categories of sources from which Personal Information is collected
      • Directly from you, or your delegate, when you submit a Form
    • Business purpose(s) for collection, use, and disclosure: 
  • To support the onboarding of current or prospective Network Participants/Technical Integrators and the testing of our products and services;
  • To communicate with you about our products and services and related documentation;
  • For operations;
  • For business partner inquiries (B2B), to send you information about our products and services that we believe you will find beneficial and to respond to your requests/inquiries and comply with your stated communication preferences;
  • To provide you with a safe, efficient, and customized experience;
  • To provide other services you request;
  • To prevent, detect, and protect against security incidents, fraud, and prohibited or illegal activities;
  • To undertake activities to verify or maintain the quality or safety of our services; and
  • To perform services (for us or our service providers) such as providing analytic services
  • Disclosed for business purpose(s) to the following categories of third parties:
  • Our customers (Network Participants, Technical Integrators)(e.g., we may disclose information with them about their users);
  • Our service providers;
  • Law enforcement, government agencies and other authorized third parties (we may be required by law to disclose information for legal reasons); and
  • Other entities with your consent
  • Sold or shared to the following categories of third parties: 
  • None 
  • Length of time Personal Information is intended to be retained: (unless we are legally obligated to hold longer)
    • Length of Network Participant or Technical Integrators relationship plus 10 years
  • Certain identifying Personal Information
    • Examples:
      • Company address, company telephone number
    • Categories of sources from which Personal Information is collected
      • Directly from you, or your delegate, when you submit a Form
    • Business purpose(s) for collection, use, and disclosure: 
  • To support the onboarding of current or prospective Network Participants/Technical Integrators and the testing of our products and services;
  • To communicate with you about our products and services and related documentation;
  • For operations;
  • For business partner inquiries (B2B), to send you information about our products and services that we believe you will find beneficial and to respond to your requests/inquiries and comply with your stated communication preferences;
  • To provide you with a safe, efficient, and customized experience;
  • To provide other services you request.
  • To prevent, detect, and protect against security incidents, fraud, and prohibited or illegal activities;
  • To undertake activities to verify or maintain the quality or safety of our services; and
  • To perform services (for us or our service providers) such as providing analytic services
  • Disclosed for business purpose(s) to the following categories of third parties:
  • Our customers (Network Participants/Technical Integrators)(e.g., we may disclose information with them about their users);
  • Our service providers;
  • Law enforcement, government agencies and other authorized third parties (we may be required by law to disclose information for legal reasons); and
  • Other entities with your consent
  • Sold or shared to the following categories of third parties: 
  • None 
  • Length of time Personal Information is intended to be retained: (unless subject to a legal hold)
    • Length of Network Participant or Technical Integrators relationship plus 10 years

Note: In the past 12 months, we have not sold, or shared Personal Information collected from Forms. For purposes of this Privacy Notice, “sale” means the disclosure of Personal Information to a third-party for monetary or other valuable consideration and “share” means the disclosure of Personal Information to a third party for cross-context behavioral advertising. This also means that we have not sold or shared information about minors.

4. California Network Participants/Business Partners (B2B) residents’ privacy rights

If you are a California resident and you’ve interacted with us on behalf of your Network Participant/company/business (i.e., you’ve expressed interest in our products/services for your financial institution), the following data privacy rights are available to you:‍‍

  • Third party direct marketing: Request a list of what Personal Information (if any) we’ve shared with third parties for their own direct marketing purposes in the preceding calendar year and the names and addresses of those third parties.‍
    • How? We do not share Personal Information with third parties for their own direct marketing purposes. Therefore, we have not shared Personal Information with third parties for direct marketing purposes within the last 12 months.‍
  • Right to Know: Know the categories and specific pieces of Personal Information we collected about you in the preceding 12 months following your request, our business purposes for collecting Personal Information, the categories of sources that we’ve collected Personal Information from, the categories of third parties that we’ve disclosed Personal Information to, whether we’ve sold or shared Personal Information to a third party in the preceding 12 months, and the categories of third parties with which we’ve sold or shared Personal Information.‍
    • How? Review this Privacy Notice in its entirety to learn more about the Personal Information we collect, why we collect Personal Information, the sources from which we collect Personal Information from, and who we may disclose Personal Information to. To submit a California Network Participants/Business Partner (B2B) Data Privacy Rights Request, see the below for instructions.‍

Note: You may request that we disclose the above information beyond the 12-month period for Personal Information collected on or after January 1, 2022, unless doing so proves impossible or would involve a disproportionate effort.

  • Right to Correct Inaccurate Data: Request that we correct inaccurate Personal Information that we maintain about you.‍
    • How? Review this Privacy Notice in its entirety to learn more about the Personal Information we collect, why we collect Personal Information, the sources from which we collect Personal Information from, and who we may disclose Personal Information to. To submit a California Network Participants/Business Partner (B2B) Data Privacy Rights Request, see the below for instructions.

      Note: To the extent required by, and in accordance with applicable law, we will use commercially reasonable efforts to correct your Personal Information as directed by you, considering the nature and the purposes of maintaining your Personal Information. Under certain circumstances, we may not be able to correct your information because we have a legal obligation or other reason in which we must retain it in its current state (e.g., the nature of the data, the source of the data, to comply with law).
       
  • Right to Delete Data: Request that we delete your Personal Information.
    • How? Review this Privacy Notice in its entirety to learn more about the Personal Information we collect, why we collect Personal Information, the sources from which we collect Personal Information from, and who we may disclose Personal Information to. To submit a California Network Participants/Business Partner (B2B) Data Privacy Rights Request, see the below for instructions.

      Note: Under certain circumstances, we may not be able to delete your information because we have a legal obligation or other reason that we must retain it.
       
  • Right to Limit Data: Limit the use of sensitive Personal Information.
    • How? Our Forms do not collect sensitive Personal Information.
  • Right to Opt Out: Opt out of the sale or sharing of your Personal Information.
    • How? In the past 12 months, we have not sold or shared Personal Information from Forms. For purposes of this Privacy Notice, “sale” means the disclosure of Personal Information to a third-party for monetary or other valuable consideration and “share” means the disclosure of Personal Information to a third party for cross-context behavioral advertising.
  • Right to Not Be Retaliated Against: Be free from retaliation for exercising your privacy rights.
    • How? We will not retaliate against you for exercising your privacy rights.

Instructions for Submitting a California Network Participants/Business Partner (B2B) Data Privacy Rights Request

To submit a California Network Participants/Business Partner (B2B) Data Privacy Rights Request, send an email to Zelleprivacy@earlywarning.com with "California Network Participants/Business Partner (B2B) Data Privacy Rights Request" in the subject line. In the body of the email, please include:‍‍

  • Your first name
  • Your last name
  • The name of your financial institution/business/company
  • Your business email address or business telephone number
  • Your California address
  • Your business relationship with us (financial institution/business partner)
  • Your request (access, correct, or delete personal information)

Please note the above-listed rights are subject to certain exceptions. For instance, we cannot disclose or permit access to specific pieces of Personal Information if the disclosure or access would present a certain level of risk to the security of the Personal Information, your account with us or the security of our systems or networks. We may decline your request if we cannot verify your identity or confirm the Personal Information that we maintain belongs to you. If we cannot honor your request, we will let you know. 

Upon receipt of your “California Network Participants/Business Partner (B2B) Data Privacy Rights Request” email, we will acknowledge receipt of your request and let you know how long we expect it will take us to complete your request (typically 45 days or less for most requests).

When you make a request, we will attempt to verify that you are who you say you are. For example, we will attempt to match information that you provide in making your request with information that we have on file. We may need to request additional information from you to verify your identity or to understand the scope of your request, although you will not be required to create an account with us to submit a request or have it fulfilled.

You may designate an authorized agent to make a request on your behalf. Your authorized agent will be required to produce a signed authorization from you and additional identity verification may be required. Authorized agent requests may be made by sending an email to zelleprivacy@earlywarning.com.

5. Your choices

If you’ve previously expressed interest in our products and services for your company/business and you no longer wish to receive marketing communications from us, you can indicate your communication preference within the direct communication from us (e.g., using the unsubscribe link in the email you receive from us) or by emailing marketing@earlywarning.com. Please allow us a reasonable period of time in order to satisfy your request, as some communications may already be in process.

6. How we protect Personal Information

To help us protect your Personal Information, we maintain technical, physical, and administrative security measures to protect against loss, misuse, unauthorized access, disclosure, or alteration. Some of the safeguards we use are firewalls, data encryption, physical access controls to our data centers and information access authorization controls. 

7. Where Personal Information is stored

We are located in the United States. Our operations use a network of computers, cloud-based services, and other infrastructure and information technology that are based in the United States. Additionally, we may use third-party service providers that may process and/or store your Personal Information in the United States, the European Union, and in other countries. 

8. Changes to this Privacy Notice

From time to time, we may update this Privacy Notice. You agree that we may notify you about material changes in the way we treat Personal Information by email or by placing a notice on this website.

9. How to contact us

If your questions are not answered in this Privacy Notice, you may email us at zelleprivacy@earlywarning.com, or write to us at Early Warning Services, LLC., Attn: Privacy Office, 5801 N Pima Rd, Scottsdale, AZ 85250.
Zelle® Trademark Guidelines | Brand Usage and Legal Information

Zelle® Trademark Guidelines

The Zelle® Trademark Guidelines (“Guidelines”) are intended for licensees, authorized resellers, resellers, customers, and other third parties that intend to use any of the Zelle® Marks (defined below) in promotional, instructional, reference materials, or any other public facing materials. Licensees of the Zelle® Marks will have been provided with trademark usage terms. In the event there is a conflict between any trademark usage terms and these Guidelines and any license grant, the trademark license grant terms will control the licensee’s use of the Zelle® Marks.

The “Zelle® Marks” include the standard character Zelle® trademarks owned and used by Early Warning Services, LLC (“Early Warning”), a non exhaustive list provided below.

This list is subject to change with out notice:

     Zelle®

     Zellepay®

     Zelle Network®

     Zelle. This is How Money Moves®

     Zelle | This is How Money Moves ®

     Zelle This is How Money Moves®


By using a Zelle® Mark, in whole or in part, you are acknowledging that Early Warning is the sole owner of the Zelle® Mark and promising that you will not interfere with rights held by Early Warning in the trademark, including challenging any use, registration of, or application to register such trademark, alone or in combination with other words, anywhere in the world by Early Warning, and that you will not harm, misuse, or bring into disrepute any Zelle® Marks and/or Early Warning trademark. The goodwill derived from using any part of a Zelle® Mark exclusively inures to the benefit of and belongs to Early Warning. Except for the limited right to use as expressly permitted under these Guidelines, no other rights of any kind are granted hereunder, by implication or otherwise.

The Zelle® related trademarks and service marks that are stylized, slogans/taglines, and Zelle® logos owned and used by Early Warning may only be used under a license grant from Early Warning or an appropriate sub license grant from an entity with the rights to provide a sub license. To be clear, stylized Zelle® marks, slogans/taglines, and Zeller® logos are not included in the definition of Zelle® marks and are not addressed by this document. Early Warning takes great care in the development and protection of its Zelle® Marks and reserves all rights of ownership of its Zelle® Marks and the goodwill created in association with their use.


Fair Use of Trademarks by 3rd Parties

“Fair Use” of the Zelle® Marks, in other words any use of the Zelle® Marks by a third party without express permission or license can only apply to plain text (e.g., standard character) references to Zelle® Marks and Zelle® services. Fair Use does not extend to any Zelle® logos or stylized trademarks.

In general, Fair Use references to Zelle® marks must be truthful, must not mislead the public, and must not damage or misappropriate the goodwill associated with the Zelle® Marks. The Fair use of Zelle® Marks must accurately reference, explicitly or implicitly, the relationship between your company, products or services, and the Zelle® Marks and Early Warning. In general there are two types of acceptable fair use:

  1. When referencing the specific Zelle® service, and
  2. When indicating a third party service or product is compatible with, or provides a legitimate Zelle® service.


It is important to note that when fair use is being made of the Zelle® Marks that the Fair Use Guidelines below are followed. If the Fair Use Guidelines below are not followed the use of the Zelle® Marks may be considered unfair and a misappropriation of the rights of Early Warning.


Fair Use Guidelines for Use and/or Reference of the Zelle® Marks

Zelle® Marks (e.g., the Zelle® standard character marks) may be used to identify Zelle® products and services on websites; instructional, promotional, and/or reference material(s); or in the titles of publications, conferences, and/or seminars that feature or reference Zelle® products or services, provided the following Guidelines are met:

  1. May not include Zelle® Marks in your company name, product or service name(s), domain name(s), mobile app name(s), social media account name(s), publication title(s), conference title(s), website name(s), or any other source identifying material(s), without express prior authorization from Early Warning.
  2. May not include Zelle® Marks, in whole or in part, in your company logo(s), product logo(s), app launch tile image(s), in your software product(s) or service(s), social media profile page(s) or community image(s) without a prior written license/authorization from Early Warning.
  3. Your company name, product or service name(s), domain name(s), mobile app name(s), social media account name(s), publication title(s), conference title(s), website name(s), or any other source identifying material(s) may not be confusingly similar to the Zelle® Marks. Additionally the Zelle® Marks may not be used in the domain name of any publication, conference or seminar website without a written license or equivalent authorization from Early Warning.
  4. May not use Zelle® Marks on or in connection with any obscene or pornographic materials, or illegal activity, and use of Zelle® Marks may not be disparaging, defamatory, or libelous to Zelle® and/or Early Warning, any of its products, or any person or entity associated with Zelle® and/or Early Warning.
  5. May not use Zelle® Marks in any manner that directly or indirectly expresses or implies Zelle® and/or Early Warning sponsorship, affiliation, certification, approval, or endorsement in relation to your product(s), service(s), publication(s), conference(s), or seminar(s) or in such a manner that it appears that the Zelle® services and/or Early Warning is legally associated with your company, product(s), service(s), publication(s), conference(s), and/or seminar(s).
  6. May not use Zelle® Marks on or in connection with a website that provides download links for a fee (whether directly or indirectly via a subscription model or the like) for any Zelle® product or service.
  7. Zelle® Marks may not be the most prominent visual element(s) on a download page, app store marketing, or other marketing materials for your product or service. Your company name or logo, product or service name, and graphic identity must be significantly larger than Zelle® Marks. For conferences, publications, or seminars the Zelle® Marks may not appear larger or more prominent than the title or author’s name on the cover of the publication and in all materials related to the conference or seminar.
  8. May not alter Zelle® Marks in any way that results in changing a Zelle® Mark’s visual appearance, including, but not limited to, combining additional words or designs with Zelle® Marks, or removing a portion or portions of Zelle® Marks.
  9. Must always include the following trademark attribution statement: “All Zelle® trademarks used herein, are the exclusive property of Early Warning Services, LLC and are used with permission.”
  10. Must include a conspicuous disclaimer wherein it is made clear that Early Warning does not endorse or sponsor your company, any product or service offered by your company, or any publications, presentations, or distributed materials from your company. For uses of Zelle® Marks with products or services, at a minimum, the following disclaimer is an example of an acceptable disclaimer that must appear on any website or mobile application displaying a Zelle® Mark, and state in all capital letters:


“[INSERT PRODUCT or SERVICE] IS NOT AUTHORIZED, ENDORSED, OR SPONSORED BY EARLY WARNING SERVICES, LLC- OWNER OF [INSERT List of Zelle® Marks used].”

For uses of Zelle® Marks in publications, presentations, or distributed material, at a minimum, the following disclaimer is an example of an acceptable disclaimer that must appear in all capital letters:

“[INSERT TITLE OF PUBLICATION, CONFERENCE or SEMINAR] IS NOT AUTHORIZED, ENDORSED, OR SPONSORED BY EARLY WARNING SERVICES, LLC- OWNER OF [INSERT List of Zelle® Marks used].”
 

  1. May not manufacture, sell, or give-away merchandise items, such as T-shirts and mugs, bearing Zelle® Marks.
  2. Early Warning reserves the right to revoke at any time, in its sole discretion, any permission granted to use Zelle® Marks, unless specifically prohibited in a separate agreement.
  3. May not purchase any Zelle® Marks as ad words or advertising keywords from any search engine, social media forum, or other online venue without express written authorization from Early Warning, which permission may be withdrawn if these Guidelines are violated.
  4. Must use an appropriate generic term after a Zelle® Mark the first time the Zelle® Mark appears in a publication and as often as possible after that. Any use of a Zelle® Mark must not be as a verb or noun and the use must always be as a descriptor acting on the goods or services being offered under the Zelle® Mark.

For example:

Acceptable: Disburse money with Zelle® payments

Unacceptable: Zelle® your funds

Americans Rely on Zelle® | Fraud Prevention, Security and Facts

Exposing the False Claims Against Zelle®: The Political Misinformation Driving the Lawsuit Against Zelle

Americans Rely on Zelle

Zelle® is one of the most relied on digital payment networks in the U.S., enabling consumers and small businesses to send over $1 trillion last year alone. With 2,300 banks and credit unions offering Zelle – most of them community financial institutions – it delivers reliable, fast, and free* payments directly through consumers’ bank accounts with the same bank-level protections you get from your banking app today.

While recent headlines around the New York Attorney General Letitia James’ lawsuit have raised questions, the facts tell a different story. Zelle remains committed to protecting users, fighting fraud, and providing safe payment experiences for millions of Americans every day.

Why Millions Rely on Zelle®

  • Over $1 trillion was sent using Zelle in the U.S. last year by consumers and small businesses seeking secure, embedded payment experiences. Zelle is secure because you don't have to provide bank account information like other peer-to-peer apps.
     
  • Zelle operates within a regulated banking environment, ensuring user protection and compliance with the same bank-level protections you get from your banking app today.
     
  • Designed to support the needs of New York’s consumers, small businesses, community banks and credit unions.
     
  • Enables fast, easy and free payments for millions of consumers in New York and nationwide to send and receive payments easily and for free.*
American rely on Zelle

Addressing the New York Attorney General’s Lawsuit

  • The New York Attorney General’s lawsuit is a politically motivated stunt, mirroring a CFPB suit that was already dismissed in March.
     
  • This legal action won’t stop fraud. It could encourage false claims from criminals that are seeking to game the system and create a blueprint for criminals to exploit.
     
  • Rather than protect consumers, the lawsuit increases fraud risk and could drive up costs for everyone.

Zelle® Leads in Fighting Fraud & Scams

  • Today, only 0.02% of all Zelle transactions involve a report of scam or fraud. That means more than 99.98% of Zelle transactions are without report of fraud or scam, an extraordinary rate in payments.
     
  • Zelle continues to invest in security features, fraud education, and consumer fraud and scam protections.
     
  • Zelle works closely with partner banks and credit unions to detect and respond to suspicious activity in real-time.

Where Fraud Really Happens & Why the Lawsuit Misses the Mark

  • Scams don’t originate on Zelle®. They start with criminals contacting users via social media, email, phone calls, texts, and online marketplaces.
     
  • The lawsuit ignores the root of the problem: organized domestic and foreign fraud networks targeting U.S. consumers.
     
  • Encouraging no-consequence reimbursement policies invites fraudulent claims and shifts costs to legitimate users.


Zelle is designed with consumer safety in mind. With only 0.02% of transactions today involving any fraud report, Zelle continues to be a top choice for digital payments. This lawsuit doesn’t protect users—it undermines trust and empowers criminal fraudsters.

*Based on a Q4 2024 survey of financial institutions offering Zelle® to their customers, 99.36% of consumer saving and checking accounts linked to Zelle® do not charge a fee to send, receive, or request money.

What You Need to Know: What Leticia James Gets Wrong

While New York Attorney General Letitia James has made misleading and politically motivated claims about safety and fraud rates related to Zelle®, the facts tell a very different story. Zelle leads the industry in fraud prevention, and today, only 0.02% of all Zelle transactions involve a report of scam or fraud. That means more than 99.98% of Zelle transactions are without report of fraud or scam, an extraordinary rate in payments.

  • The $1 Billion Losses Claim Is False: the claim by Attorney General Letitia James that “users lost more than $1 billion” is false and misleading.
     
  • It’s unclear how the AG’s office calculated this number, but it likely reflects reported fraud claims, not confirmed payments fraud. Not every reported fraud claim is actual payments fraud. Each claim is investigated, and in many cases, it is determined that no fraud occurred. Below are examples of situations where a customer reported fraud, but the investigation could have confirmed no fraudulent activity:
     
    • A customer may mistakenly report a forgotten purchase as a fraudulent transaction.
    • Criminals may try and exploit the network by purposefully filing false claims.
    • There may be another joint account owner on the bank account who sent a payment.  
    • A customer may make a payment to a contractor who doesn’t adequately complete agreed upon work. The customer may then file a fraud claim, but this is not payments fraud.
       
  • No Investigation Was Ever Conducted by the NY AG: Despite her public allegations, Attorney General Letitia James never conducted an investigation into Zelle. If she had, she would have seen that today, only 0.02% of all Zelle transactions involve a report of scam or fraud. That means more than 99.98% of Zelle transactions are without report of fraud or scam, an extraordinary rate in payments.
     
  • Extremely Low Fraud Rates: Zelle has consistently maintained industry-leading safety metrics, with less than 0.1% of transactions reported as involving fraud or scams since launch in 2017. Today, only 0.02% of all Zelle transactions involve a report of scam or fraud. That means more than 99.98% of Zelle transactions are without report of fraud or scam, an extraordinary rate in payments.
     
  • Consumer Protections Were Not “Just Added”: Contrary to claims, Zelle consumer protection measures did not start in 2023. The Zelle Network® has had layered fraud prevention protocols in place since day one, including advanced data-driven fraud detection.
     
  • How Zelle Helps Protect Your Money: Zelle is a secure platform when used as designed with state-of-the-art technology to monitor, detect, and prevent fraud. Participating financial institutions and Early Warning Services, the company behind Zelle, use a multi-layered approach to help protect consumers across every transaction.
     
  • Zelle Requires Reimbursements for Confirmed Fraud: Zelle goes above and beyond federal law (Reg E) by requiring financial institutions in the network to reimburse users 100% for confirmed fraud cases, as well as in eligible authorized imposter scams.
     
  • Zelle Is Free* for Consumers and Good for the Economy: Offered generally at no cost to consumers, Zelle helps drive local economic activity and modernizes how Americans send money. Reliably, quickly, and through their trusted bank.


Despite misleading claims from Attorney General Letitia James, the data shows that Zelle maintains a reported fraud rate of only 0.02%. As Zelle continues to evolve, it stays focused on protecting users, combating scams, and delivering secure, bank-integrated payments nationwide.


*Based on a Q4 2024 survey of financial institutions offering Zelle® to their customers, 99.36% of consumer saving and checking accounts linked to Zelle® do not charge a fee to send, receive, or request money.


What Could Happen if the New York AG Lawsuit Succeeds

If the lawsuit filed by New York Attorney General Letitia James succeeds, it could have serious unintended consequences for consumers, small businesses, and the thousands of financial institutions that power Zelle®. Rather than reducing fraud, this legal action risks encouraging scammers and undermining a critical payment platform relied on by millions. Understanding the real impact is critical to separating fact from fiction.

  • Criminals Would Get a Blueprint for Guaranteed Payouts: If Attorney General Letitia James’ lawsuit succeeds, it would encourage scammers by guaranteeing reimbursements with no consequences, leading to a surge in fraud and scams. That would harm New Yorkers, not protect them. Criminals quickly adapt, and guaranteed payouts would open the floodgates to more scams, not less.
     
  • Small Businesses Would Suffer: Many small business owners rely on Zelle to manage cash flow quickly and securely because they don’t have to provide their account information. The lawsuit would disrupt this critical tool, harming businesses’ ability to make timely decisions such as paying employees, purchasing supplies, or investing in growth. This would ultimately impact families and local economies.
     
  • Community Banks and Credit Unions Would Bear Unfair Costs: The lawsuit would shift the financial burden of fraud onto thousands of community banks and credit unions. Many of these institutions, including minority-owned banks and credit unions, already operate on thin margins. These institutions may be forced to either raise fees for consumers or stop offering Zelle services, reducing competition and consumer choice.


Ultimately, the lawsuit threatens to increase fraud risks, harm small businesses, and impose unfair costs on community banks and credit unions, many of which serve minority communities.

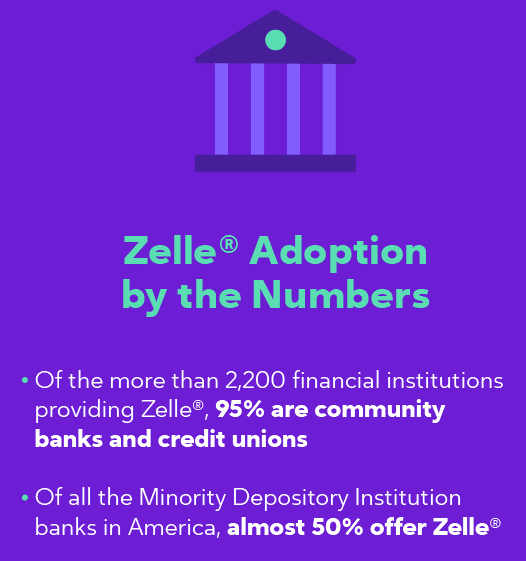
Zelle Adoption by the Numbers
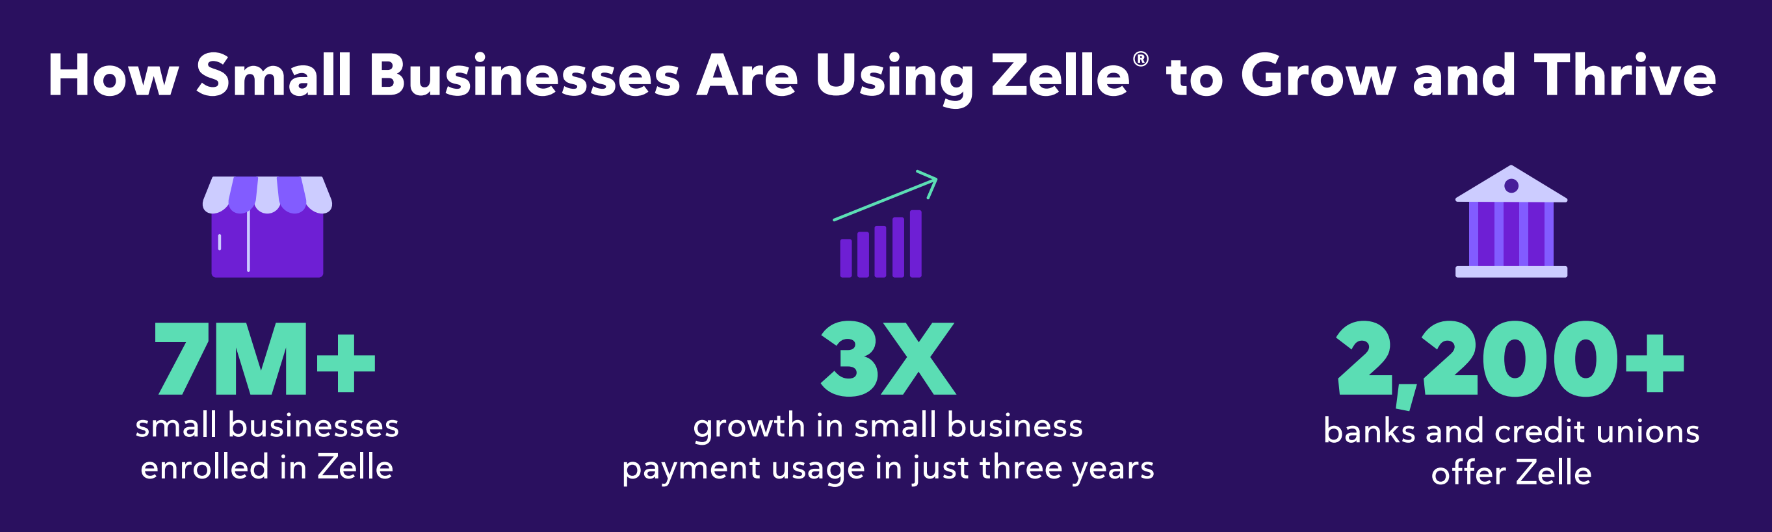
over 7 million small businesses are enrolled with zelle

Where Fraud Really Begins and How to Stop It

Americans understand that the real solution isn’t chasing fraud after it happens—it’s stopping criminals before they ever get close to the money.

Fraud and scams begin much earlier than the payment method through deceptive tactics such as phone calls, texts, and online ads used by criminals to trick consumers. Effectively combating these threats requires cross-industry collaboration among government agencies, social media companies, telecom providers, and financial institutions – for example:

  • Increasing resources for law enforcement to identify and prosecute wrongdoers and criminal penalties for the bad actors who are responsible for perpetrating fraud and scams.
     
  • Requiring mobile network operators to fully block spoofed calls, which will stop bad actors from falsifying their identities on phone calls.
     
  • As Attorney General Letitia James has also acknowledged, it's critical to hold social media companies accountable for scams on their platforms. She recently urged Meta to do more to protect Facebook users from fraudulent investment ads.


Key solutions include stronger law enforcement efforts, blocking spoofed calls by mobile operators, and social media platforms taking responsibility for stopping fraudulent content. Supporting bipartisan measures like the TRAPS Act can further empower a coordinated response to disrupt criminal networks and create a safer digital payments ecosystem for all.


Zelle® Is Helping Lead the Fight Against Fraud and Scams

Zelle and Early Warning Services are at the forefront of helping protect consumers and the financial system from fraud. With industry-leading tools, strong partnerships, and a proactive approach, Zelle continues to set the standard for security and scam prevention.

  • Working together with law enforcement, Zelle and its partner banks and credit unions actively help identify and hold criminals accountable.
     
  • Using cutting-edge fraud intelligence technology, Zelle doesn't just respond to fraud. It works to keep bad actors out entirely. Early Warning’s success is so strong, it's now advising the U.S. Treasury and Federal Reserve on fraud prevention for FedNow.
     
  • Zelle empowers users with fraud education, delivering timely scam awareness messages to millions of users nationwide.
     
  • Partnering with organizations like Consumer Action, Zelle is conducting nationwide fraud prevention workshops for local communities.
     
  • Zelle plays a national leadership role, serving on the Aspen Institute's Task Force on Fraud and Scam Prevention to tackle fraud as a public safety and economic threat.


Even with fraud and scam rates already extremely low, Zelle remains committed to driving industry-wide innovation in consumer protection and scam prevention.

Nothing will change that.

Join the Zelle® Network | Payment Solutions for Financial Institutions

Innovation.
Powered by partnerships.

Zelle® connects financial institutions of all sizes across the U.S. to make it fast and easy to send and receive money.

Learn more about how to join our growing list of financial institution partners.

What we offer.

PAYMENT SOLUTIONS

We provide a simple framework to enable person-to-person payments, small business payments, and disbursements through one recognizable, consistent consumer brand.

CUSTOMER EXPERIENCE

Win new customers or members and strengthen relationships with existing. Improve customer experience through expanded capabilities.

NATIONWIDE NETWORK

Over 143 million consumers1 can experience Zelle® through the mobile banking apps of the Zelle® network participant financial institutions.


Partner with us.

Zelle® connects financial institutions to make it fast and easy for their consumers and small businesses to send and receive money since the creation of the Zelle® network in 2017.

FINANCIAL INSTITUTIONS1

2400+

NETWORK VOLUMES2

$1T+


TRANSACTIONS2

5B+


PROCESSOR PARTNERS

Alacriti
FIS
fiserv
jack henry
Subscribe to